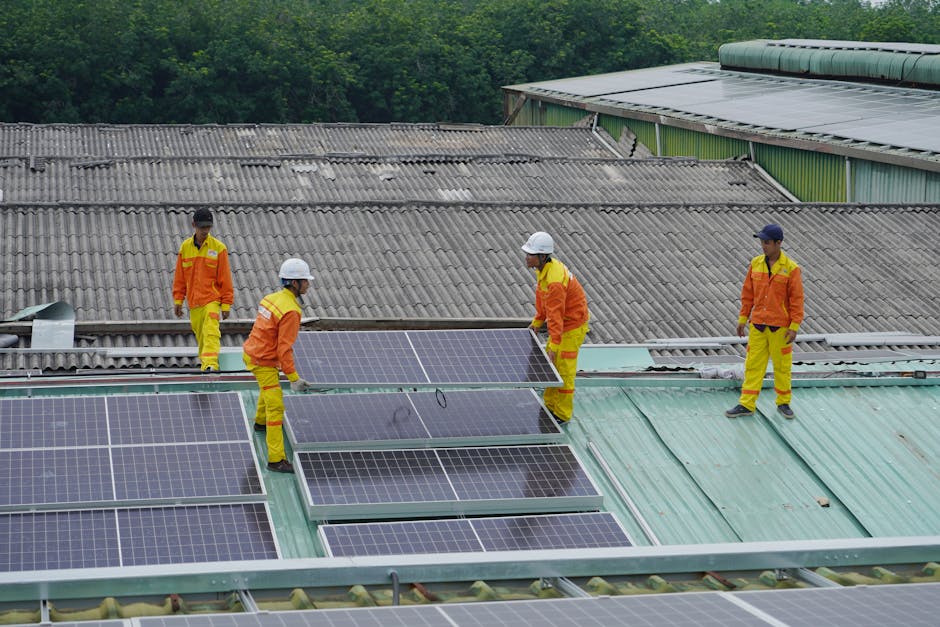
The commercial solar credit is a dollar-for-dollar reduction of your federal tax liability, not a deduction. For systems placed in service in 2026, the base rate is 30% of eligible project costs, and bonus adders can push that rate to 50% or higher depending on where and how the system is built.
What does the credit actually cover?
The credit applies to business-owned solar installations across virtually every commercial asset class: office buildings, warehouses, retail centers, industrial facilities and agricultural operations. Eligible costs include:
- Solar panels, inverters, racking and mounting hardware
- Monitoring equipment, conduit and wiring
- Contractor installation labor
- Permitting fees and engineering costs directly tied to the solar project
Costs that do not count toward the eligible basis include land, roof repairs that would have been needed regardless of the solar installation, and general electrical upgrades that serve the building broadly rather than the solar system specifically.
The credit can be claimed by C-corporations, S-corporations, partnerships, LLCs and REITs. Tax-exempt organizations and government entities can elect to receive it as a direct cash payment from the Treasury under Section 6417 of the Inflation Reduction Act. For authoritative definitions of qualifying energy property, see the IRS guidance on the Investment Tax Credit.
How does the math work in Year 1?
Here is a straightforward example. A business owner installs a solar system on a warehouse at a total project cost of $1,000,000.
- Eligible basis: $1,000,000
- Base credit at 30%: $300,000 applied dollar-for-dollar against federal tax owed
When a taxpayer claims the credit, the IRS requires a reduction in the depreciable basis of the property by 50% of the credit amount. In this example, the $1,000,000 basis is reduced by $150,000 (50% of the $300,000 credit), leaving an adjusted depreciable basis of $850,000.
Solar equipment is classified as 5-year MACRS property. Bonus depreciation is currently 100% for qualified property acquired after January 19, 2025, so the entire $850,000 adjusted basis can be deducted in Year 1. For a business owner in the 37% marginal bracket, that depreciation deduction generates an additional $314,500 in tax reduction on top of the $300,000 credit itself.
The combined Year 1 tax benefit on a $1,000,000 investment can be substantial before a single dollar of electricity savings is counted. For more on how bonus depreciation interacts with solar property, see our post on How Does Solar Depreciation Work for High Earners in 2026?
What bonus adders can increase the credit above 30%?
The Inflation Reduction Act created several bonus adders that stack on top of the base rate.
Energy Community Bonus (+10%): If the system is installed in an energy community, defined as a brownfield site, a census tract where a coal mine or coal-fired power plant has closed, or an area meeting fossil fuel employment thresholds, the effective credit rate rises to 40%. The Department of Energy maintains a mapping tool to verify eligibility by address before a project begins.
Domestic Content Bonus (+10%): Projects that use domestically manufactured steel, iron and components meeting a 40% domestic content threshold qualify for an additional 10 percentage points. Verifying this requires component-level certifications from equipment suppliers and contractors at the procurement stage. Retroactive certification is significantly harder to substantiate. The IRS guidance on energy credit bonus adders explains how Treasury defines and measures this threshold.
Low-Income Community Bonus (+10% to 20%): Under the applicable IRA provisions, systems in qualified low-income census tracts or on tribal land may qualify for an additional 10% or 20% bonus. This adder requires an application to an IRS allocation program that operates on an annual capacity basis. Demand consistently exceeds supply, so early application matters.
Stacking all three adders on a qualifying project can push the effective credit rate to 60% or more.
Curious how this applies to your situation?
See the strategies built for high earnersWhat mistakes most often kill a legitimate claim?
Claiming the credit before the system is operational. The credit is available only in the tax year the system is placed in service, meaning fully operational and capable of generating electricity. Invoice date, delivery date and construction start date do not qualify. Claiming the credit early creates audit exposure.
Ignoring prevailing wage and apprenticeship rules. For systems at or above 1 megawatt of nameplate capacity, failure to comply with prevailing wage and apprenticeship requirements collapses the base credit rate from 30% to 6%. On a $2,000,000 system, that is the difference between a $600,000 credit and a $120,000 credit. Contractors must maintain certified payroll records, and taxpayers must retain that documentation. Projects under 1 megawatt are automatically exempt from these requirements.
Forgetting the basis reduction. Claiming the credit without reducing the depreciable basis by 50% of the credit amount results in overstated depreciation deductions that the IRS will disallow on examination.
Mishandling passive activity limitations. For investors who are not materially participating in the business that owns the solar system, the credit may be limited by passive activity rules under Section 469. Credits from passive activities can generally only offset tax on passive income. IRS Publication 925 covers how passive activity and at-risk rules apply to energy credits. For a deeper look at how material participation affects these strategies, see our post on How Does Material Participation Work for Short-Term Rentals?
Missing the carryforward and carryback option. If the credit exceeds current-year tax liability, it can be carried back one year and forward up to 20 years. Taxpayers who overlook the carryback leave potential cash refunds unclaimed.
Can unused credits be sold to someone else?
Yes. Under Section 6418 of the Inflation Reduction Act, taxpayers who generate more commercial solar credit than they can absorb in a given year may sell those credits to unrelated third-party buyers for cash. The seller receives immediate cash; the buyer receives a dollar-for-dollar credit against their own tax liability. Current market pricing for transferred credits is typically 90 to 95 cents on the dollar.
This mechanism makes solar investment viable even for businesses with temporarily reduced tax liability in a given year. For transfer mechanics and election procedures, see the Treasury Department's guidance on ITC transferability under Section 6418.
What does the 2026 construction timeline mean for new projects?
For projects that began construction on or before July 4, 2026, there is no placed-in-service deadline tied to the current credit framework. For projects that began construction after July 4, 2026, the system must be placed in service by December 31, 2027 to qualify.
Contractor capacity is finite, permitting timelines vary by jurisdiction, and utility interconnection can add weeks to a project schedule. Every credit claim flows through IRS Form 3468 and then onto Form 3800. Errors in how energy credit property is classified or how the basis is calculated are a primary trigger for IRS examination of energy credit claims.
Our team works with business owners and investors to map credit absorption capacity, identify bonus adder eligibility and coordinate solar strategy with the broader tax picture, including depreciation timing and passive activity rules. For context on how these strategies fit into a larger plan, see our post on How Can High Earners Reduce Taxes in 2026?
Want to talk it through with our team?
Book a quick chatPricing depends on complexity. A quick chat is the fastest way to see if we are a fit.
DISCLAIMER: The information on this website is for educational purposes only and does not constitute professional tax, legal, or financial advice. Tax laws are complex and change frequently. Individual results will vary. We recommend consulting with qualified professionals before implementing any tax strategy. To comply with IRS Circular 230, any federal tax advice on this website is not intended to be used, and cannot be used, to avoid penalties or to promote any transaction. Use of this website does not create a professional relationship with Tax GPS Group LLC. For personalized advice, schedule a consultation with our team.